All Categories
Featured
Table of Contents
With globalization in retreat, regional blocks and brand-new rules in trade, security and currencies emerge, making it key to invest with durability and geographical/strategic diversity. We get in a more relentless inflationary regime due to structural factors and public deficit, so inflation becomes a main axis to secure long-term genuine returns.
2026 needs. however with shorter maturities, must use attractive returns with workable risk. Neutral on sovereign financial obligation from emerging markets and.: AI continues to be an essential chauffeur (higher diversity suggested). We continue to prefer Asia, with among our main convictions.: pressure persists on oil and natural gas prices, benefiting Europe.
European currencies could extend their gains, with the remaining as a. The reasonably as the effects of President Trump's trade program dissipate and the boom that implies financial investment in AI.: Japan consolidates exit from deflation with reforms and more nominal growth; China continues to be weighed down by genuine estate/consumption in the short-term, but with a structural engine in AI and technology.: neutral stance in industrialized stock due to balance in between AI advantages and valuations/tariffs.
Current GCC Equity Market Patterns to Watch
The primary risks are a possible bubble/disappointment in AI returns, political sound in the United States and geopolitical hotspots (Russia-Ukraine and others).: retail entry continues in private and AI continues to permeate portfolios. Rotation and IPOs enhance however keep an eye out for stress in venture capital/direct loaning, while hedge funds can record alpha in volatility.
Comparing Market Growth Potentials in GCC EconomiesThe ECB would adopt a more mindful position, stabilizing German financial stimulus and risks on employment and usage. The: spreads stay really tight, however backed by high corporate revenues, high margins and low default rates. The environment prefers: returns are anticipated to be aligned with current yield levels, mainly supported by the bring.
In the United States, a is preferred, combining brief duration with exposure in the 710 year variety. In financial investment grade, danger premium compression prefers a rotation from subordinated to senior debt. If there is a bubble, it is not in the innovation itself, but in the evaluations of a specific group of companies.

Emerging market financial obligation, backed by lower financial obligation levels, solid basics and less dollar reliance, offers appealing options to developed market assets.: they are not a passing trend. Their development is driven by withstanding structural factors. The recovery is underway and innovation will speed up accessibility.: sticks out for better risk-adjusted efficiency and better credit quality compared to the US.
After the last Fed rate cut, it is a mystery to know the level to which rates will drop in 2026.2026 will be favorable for equities, and in set earnings it will be needed to diversify and be selective., due to stimuli and accommodative financial policy. Among them, he sees more prospective in Japan and emerging markets due to valuations.
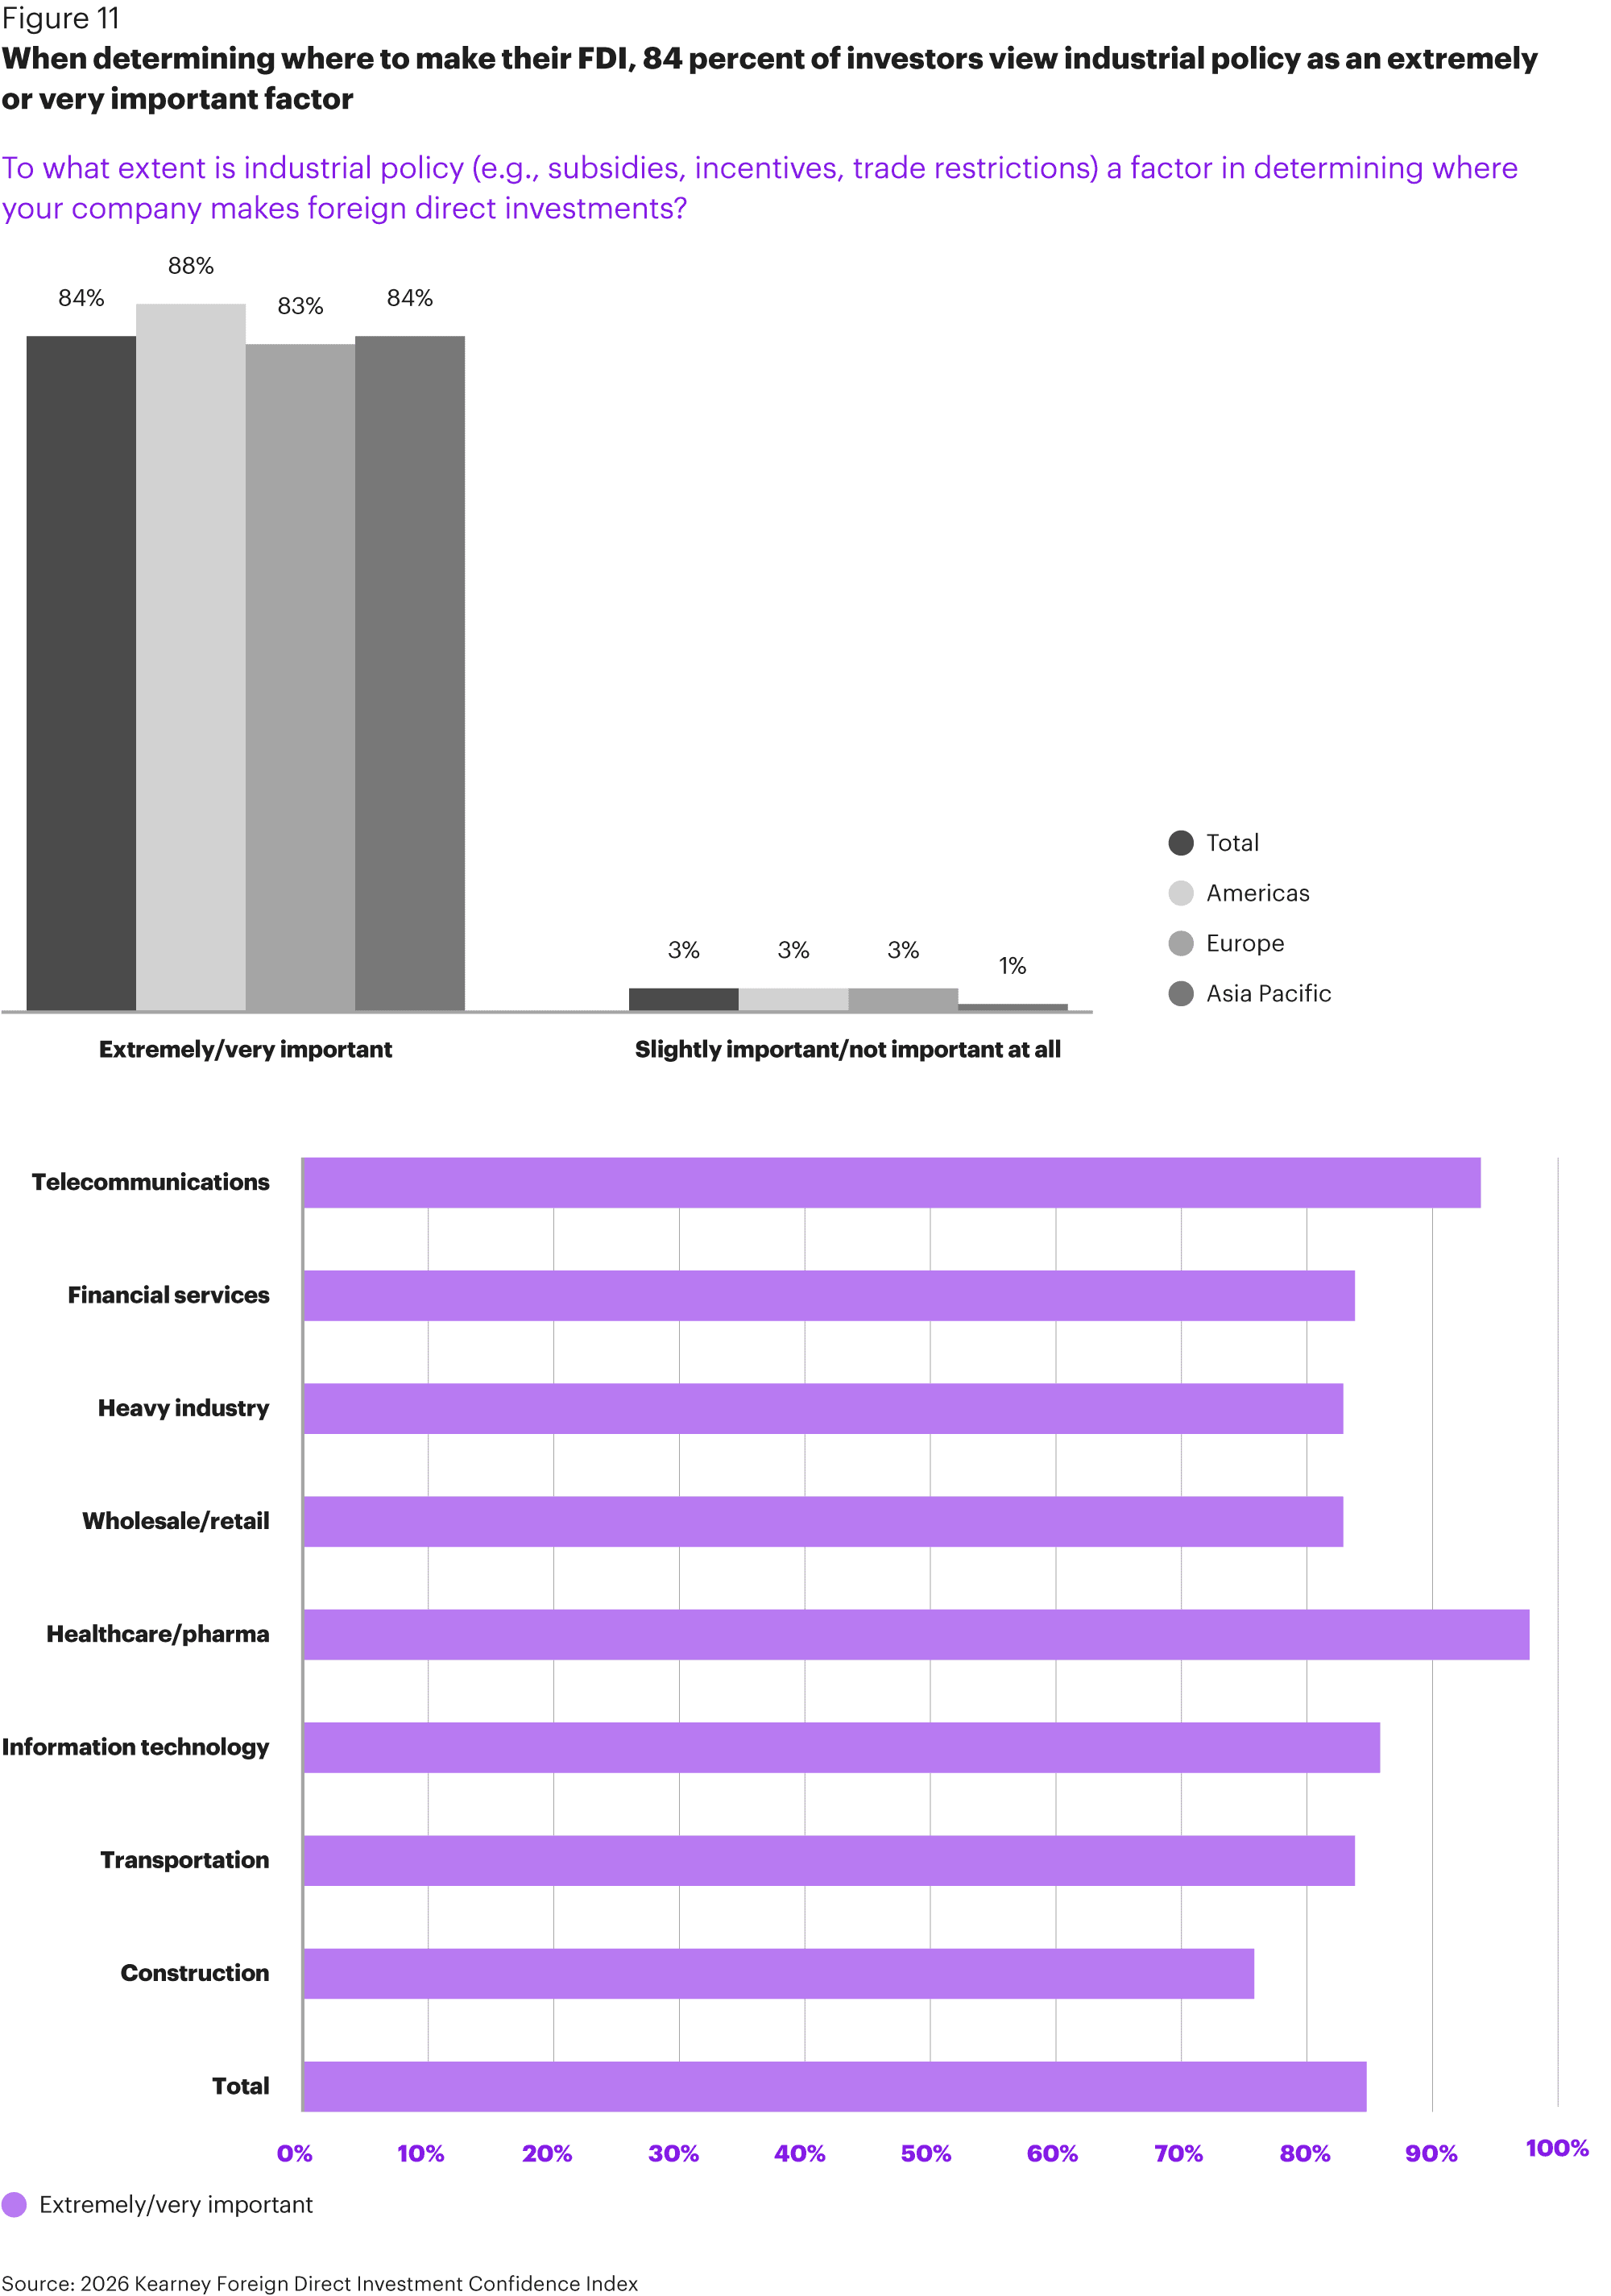
Comparing Economic Growth Potentials in GCC Nations
The of the year that will have the most influence on the markets will be Donald Trump, tariffs, reserve banks, AI, and geopolitics.: in the US, two-speed growth is anticipated to continue 2026, staying below its 2% capacity. In the Eurozone, the economic healing is gaining momentum, driven in particular by investment strategies in Germany.
In the United States, the prospects for long-term rates of interest remain more uncertain. Existing fundamentals support credit, which will be a preferred bond possession for the next year. This pattern still depends on the ability of companies to satisfy expectations. In our base hypothesis, we foresee a that would be a repeating of the 2017 conditions.
There is a risk of a drop for the.: sustainability themes progress and focus on adjusting to. In the medium term, there is concern about the boost in public debt levels and the possibility of speeding up inflation. There is a perceived.There is possible in the and great potential customers for.: offers much better dynamics and greater real returns than the financial obligation of industrialized markets.: can be thought about an essential area where cyclical and structural forces align to develop opportunities.
Capital Diversification Frameworks for a 2026 Global Market
remains a necessary possession in any allocation due to its capability to generate return, carry and capitalization. Particularly, in the field, our company believe that the basics of issuers stay strong. We continue to bank on constructing portfolios around high yield providers with reasonable debt levels and returns.Selection of instruments with lower scores, especially CCC.: the principles of the European banking sector stay strong.
Within the banking sector, it generally focuses on.Very attentive to the possible contagion of to set earnings markets.: opportunities specifically in, sectors that present attractive valuations and will benefit as soon as the current market distortions stabilize; as well as in. continues to be another appealing financial investment style.

Latest Posts
Roadmap to Gulf Financial Market Trends in 2026
The Role of Capital on GCC Economic Development
Top Foreign Investment Prospects for the GCC Market